Last updated: June 2026 · Written by the Buenos Aires Tourism editorial team
The first time I pulled cash from a machine in Buenos Aires, the ATM dinged me a flat fee worth nearly ten US dollars — on a withdrawal so small I had to come back hours later and do it again. It is the most predictable money mistake visitors make here.
Here is the short version. The ATM fees Argentina tourist guides keep warning about are punishing not because the exchange rate is bad anymore — that gap has largely closed in 2026 — but because Argentine cash machines charge a high fixed surcharge (often around US$5–10) while capping each withdrawal at roughly US$40–100. Pay a flat fee on a tiny withdrawal and you lose 10–15% before your home bank adds its own charges. The fix: withdraw rarely and large, use a fee-refunding travel card, or skip the ATM for Western Union or card payments. This guide shows you how, with every number hedged because they move fast.
ATM fees Argentina tourist guide: why withdrawals cost so much
For years the headline problem was the exchange rate: foreign cards were forced onto the lousy official rate while everyone else used the parallel “blue dollar” rate, so an ATM could quietly cost you 40–50%. That era is over. After Argentina lifted most currency controls (the cepo) in April 2025 and moved to a managed float, the official, MEP and blue rates converged — as of mid-2026 the blue dollar sits only a couple of percent above official. So the rate your ATM gives you is no longer the disaster it once was.
The killer now is the fee structure, in three layers that stack on top of each other:
- The Argentine ATM operator’s surcharge. Local banks add a fixed fee to every foreign-card withdrawal — commonly around US$5–10 as of mid-2026, often shown in pesos on a warning screen before you confirm. It is the same whether you take out US$40 or US$100, which is why small withdrawals are so wasteful.
- The low per-transaction limit. Many machines cap a single foreign withdrawal at roughly 60,000–100,000 pesos (very roughly US$40–70 at mid-2026 rates) and allow only one or two a day, so you cannot take out a week’s cash at once to amortise the fee.
- Your home bank’s charges. On top of that, your own bank may add an out-of-network ATM fee and a foreign-transaction fee, frequently another 1–3% plus a flat amount.
Put those together on a small forced withdrawal and the all-in cost routinely lands in the 10–15% range — which is what makes ATMs the most expensive routine way to get pesos in 2026. Not the rate; the fees. For how this fits your overall spending, see our complete Buenos Aires travel cost guide.
ATM costs at a glance (mid-2026, hedged — always confirm current)
| What you pay | Rough amount | Notes |
|---|---|---|
| Local ATM operator surcharge | ~US$5–10 per withdrawal | Fixed, regardless of amount |
| Typical per-withdrawal cap | ~60,000–100,000 ARS (~US$40–70) | Varies; rises with inflation |
| Withdrawals allowed per day | Often 1–2 | Card/bank-dependent |
| Your home bank’s fees | ~1–3% + possible flat fee | Waived by fee-refunding cards |
| Effective cost on a small withdrawal | ~10–15% | Why you withdraw rarely & large |
Treat every figure above as a moving target. Argentina still has elevated (if falling) inflation, so peso caps drift upward and banks tweak surcharges often. Check a live source such as dolarhoy.com or a quick Google for the current peso-per-dollar rate before relying on any number here.
Withdrawal limits and fees: what to actually expect
The number people ask me about most is the ATM withdrawal limit in Argentina, and the honest answer is “it depends on the machine, and it changes.” Foreign Visa and Mastercard withdrawals are often capped at around 60,000 to 100,000 pesos per transaction, with one or two transactions a day. At mid-2026 rates that is loosely US$40–70 a pull, though because the peso keeps weakening the screen may show more by the time you visit. Caps vary by machine, so don’t plan around any single figure.
The fee is usually flagged before you confirm: a screen reads “this operation has a cost of X pesos” — the local surcharge, roughly US$5–10 as of mid-2026. You can cancel there free if it looks outrageous, but since almost every bank charges something, hunting for a free machine is mostly futile. Better to make the fee worth paying by withdrawing as much as the cap allows.
Which banks and ATMs are least bad
No Argentine ATM is genuinely cheap for a foreign card, but a few are reliably less painful, and a couple of newer options change the game:
- Banco Nación — the state bank has historically charged one of the lower surcharges and is everywhere, including Ezeiza airport. If your card runs on the Link network, it is often the least-bad mainstream option, so try it first.
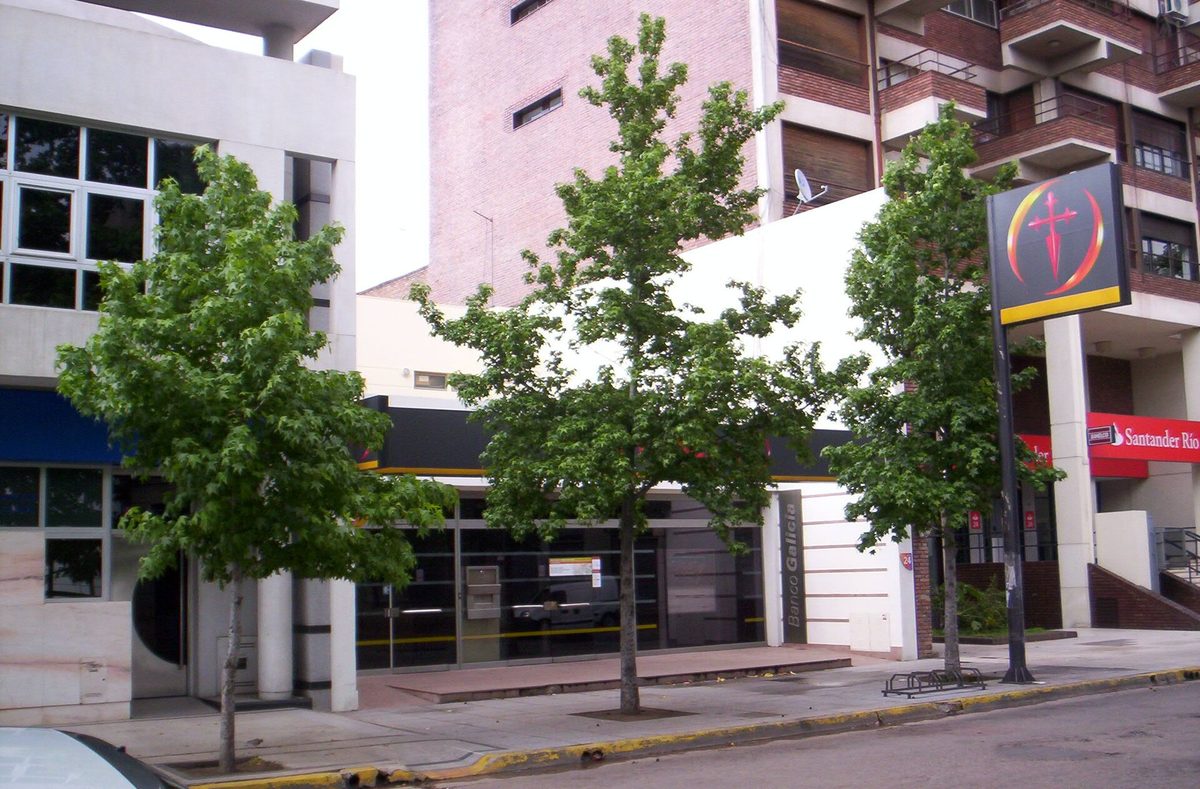
- Banco Galicia — frequently cited for higher per-withdrawal limits, which matters more than you’d think: a higher cap means you pay that fixed fee fewer times. Limits beat surcharges in the overall math.
- RedLink and Banelco are the two big networks you’ll see on most machines; fees are broadly similar, so it is the operating bank, not the logo, that sets your surcharge.
- RedATM / QR cash-out (the 2026 wrinkle) — a newer route lets some travellers pull cash via a QR code through a fintech app, often at machines inside supermarkets like Carrefour, at close to the blue-dollar rate for a fee of about a dollar or less. Availability shifts, but where offered it massively undercuts a traditional withdrawal.
The dynamic currency conversion (DCC) trap — always choose pesos
This one quietly costs more than the surcharge. Many machines ask whether you want to be charged in your home currency (US dollars, euros) instead of pesos. It sounds helpful — a familiar figure — but it is a trap called dynamic currency conversion, and the operator applies its own marked-up rate, often several percent worse than your card’s. Always decline and choose to be charged in Argentine pesos (ARS), letting your card handle the conversion. The same rule applies at shop and restaurant terminals — we cover that in our guide to paying by cash or card in Argentina.
The best bank cards for Argentina: fee-free and fee-refunding options
If you are going to use ATMs at all, the best bank card for Argentina is one that either refunds ATM fees or charges nothing extra of its own — wiping out two of the three fee layers, and in one case the local surcharge too.
- Charles Schwab (US) — the ATM champion. The Schwab Bank Visa Platinum debit card (Investor Checking account) charges no foreign-transaction fee and reimburses every ATM fee worldwide at the end of your statement cycle — including the Argentine surcharge — making it the closest thing to fee-free ATM access here. Its conversion margin is a touch higher than the fintechs, but the refunds more than make up for it. If you withdraw often, this is the card to have.
- Wise multi-currency card. No foreign-transaction fee and a small free ATM allowance each month (roughly a couple of hundred dollars before a small charge kicks in), with conversion at the mid-market rate. It doesn’t refund the local surcharge but removes your home bank’s markup.
- Revolut. Similar: fee-free withdrawals up to a monthly plan limit (higher on paid tiers), then a small percentage fee. Kills your bank’s fees, not the machine’s surcharge.
- Your everyday home debit card. Usually the worst — expect your bank’s out-of-network fee and a foreign-transaction fee stacked on the local surcharge. Fine as a backup, poor as a primary.
Whatever you carry, bring a second card from a different network as a backup — the occasional Argentine ATM rejects foreign cards.
How to minimise ATM trips
Because the surcharge is fixed, the game is paying it as few times as possible. Withdraw the maximum the machine allows every time (the fee is identical on 100,000 pesos and 40,000, so a bigger pull slashes the percentage you lose); always decline DCC and choose pesos; and carry a fee-refunding card so the surcharge comes back. Then lean on cards and QR for everyday spending so the cash lasts longer: since foreign cards now get the tourist rate, you need fewer pesos on hand. Take enough to avoid a second fee-laden trip, but don’t carry a brick of cash; petty theft is the trade-off and inflation erodes idle pesos.
When Western Union or a card beats the ATM
For most 2026 visitors, the ATM should be the backup, not the plan, and two alternatives usually win.
- Western Union. Sending money to yourself for pickup in Buenos Aires has long delivered one of the best rates available to tourists — close to or beating the blue-dollar rate — and first transfers are sometimes fee-free. You collect a stack of pesos in one trip, sidestepping the cap and surcharge entirely. The trade-offs are queues, branch hours and carrying more cash, but on rate-plus-fees it routinely crushes the ATM. We walk through it in our guide to using Western Union for the best Argentine exchange rate.
- Paying by card. Since foreign Visa/Mastercard get the favourable tourist rate, card payments are now a genuinely good deal — no surcharge, no cap, competitive rate. For anything that takes plastic, paying directly often beats withdrawing pesos to pay cash.
The ATM still earns its keep for small top-ups when you cannot reach a Western Union, for cash-only spots (some markets, small cafés, taxis, propinas) and as a safety net if a card fails — just treat it as the priciest routine option. For the full toolkit on pesos, dollars and how much cash to carry, see our Argentina currency guide for tourists.
Pros, cons and who ATMs actually suit
To be fair to the humble cajero, it is not useless — just rarely the cheapest. Pros: available everywhere, around the clock, no branch queue, a fine rate in 2026, and genuinely competitive if a Schwab-style card refunds the fee. Cons: a high fixed surcharge, low caps that force repeat trips, possible home-bank fees and the DCC skim.
Who ATMs suit: anyone with a fee-refunding card, or needing a quick top-up off-hours. Who should skip them: budget travellers and long-stayers, who save real money funnelling cash through Western Union and paying by card. Pair this with our budget day-by-day plan to keep daily peso needs low to begin with.
Frequently asked questions
How much are ATM fees in Argentina for a tourist in 2026?
Expect a fixed local surcharge of roughly US$5–10 per withdrawal, plus whatever your home bank charges (often another 1–3%). Because limits are low — frequently around US$40–70 — the all-in cost on a small withdrawal commonly works out to 10–15%. The exact peso figures drift with inflation, so confirm at the machine.
What is the ATM withdrawal limit in Argentina?
It varies by bank and machine, but foreign cards are often capped at around 60,000–100,000 pesos per transaction (loosely US$40–70 at mid-2026 rates), with only one or two withdrawals a day. Banco Galicia is often cited for higher limits. Because the peso keeps weakening, the cap you see may be higher when you travel.
What is the best bank card for Argentina to avoid ATM fees?
For ATM use, a Charles Schwab debit card is the standout: it refunds ATM fees worldwide and charges no foreign-transaction fee, effectively neutralising the local surcharge. Wise and Revolut are strong runners-up — no home-bank markup and a small free monthly ATM allowance — but they don’t refund the Argentine machine’s surcharge.
Should I use an ATM or Western Union in Argentina?
For anything beyond a small top-up, Western Union usually wins. Sending money to yourself for pickup delivers close to the blue-dollar rate, often with a fee-free first transfer, and you collect a large amount in one trip with no cap. Keep the ATM as a convenient backup for small or off-hours needs.
Can I just pay by card instead of withdrawing cash?
Largely, yes. Since late 2023 foreign Visa and Mastercard have been charged at a favourable tourist rate, so card payments are now competitive, with no surcharge and no cap. Keep some cash for markets, small cafés, taxis and tips, but for most restaurants, shops and tours, paying by card beats withdrawing pesos.
Final thoughts
The good news in 2026 is that the old Argentine money nightmare — cards forced onto a terrible rate — is gone. The bad news is the ATM kept its sting: a fat fixed fee and a stingy cap that make small withdrawals an expensive habit. So treat the cajero as your backup, not your bank: carry a fee-refunding card, withdraw big and rarely, always pick pesos, and route most cash through Western Union and most spending through a card. Do that and the “insane ATM fees” older guides warn about simply stop applying to you. For everything else, start with our Buenos Aires travel cost guide and round it out with our broader Buenos Aires travel tips.
Photo credits
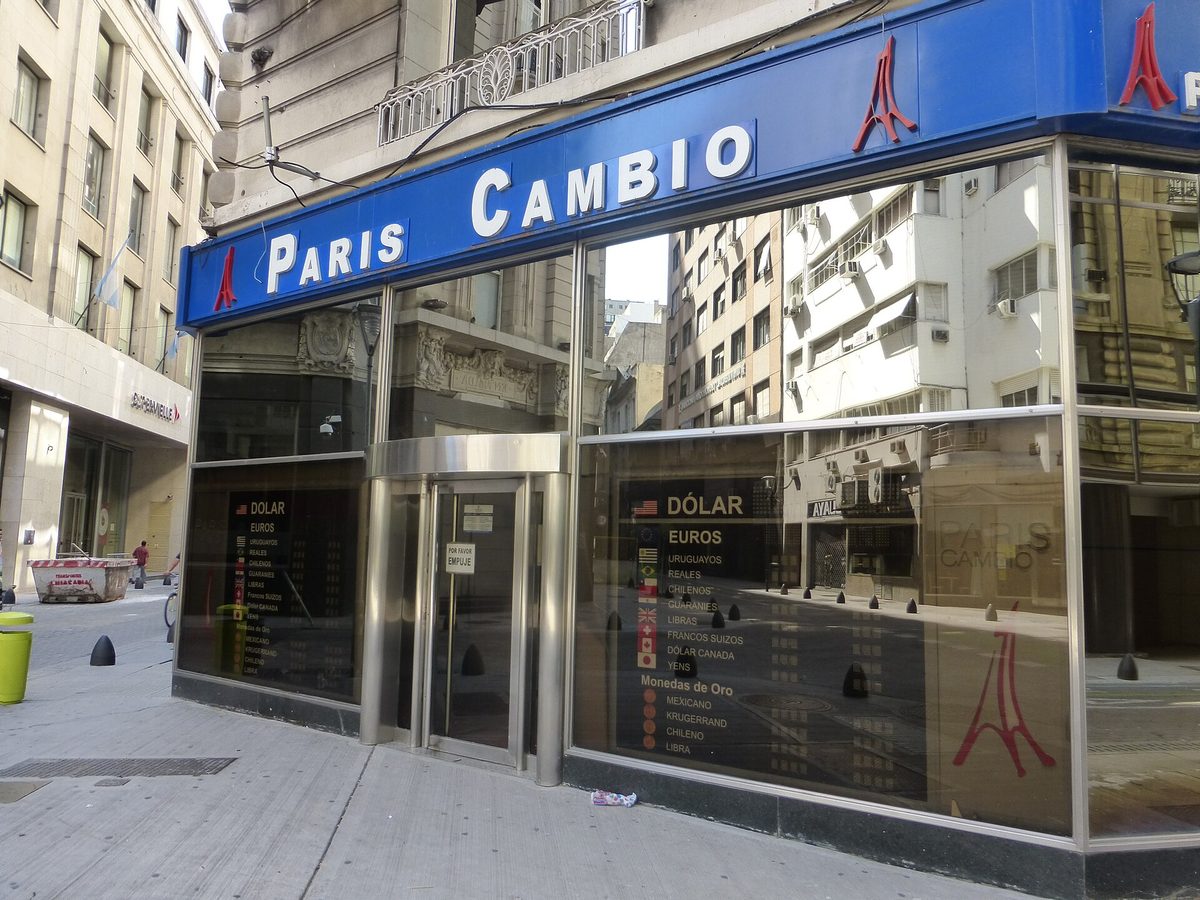
- Casa de cambio in Buenos Aires — Photo: Banfield / CC BY-SA 2.5 ar via Wikimedia Commons (file page).
- Banco Galicia branch, Argentina — Photo: Germanramos (CC0 / public domain) via Wikimedia Commons (file page).
- Calle Florida, central Buenos Aires — Photo: Gobierno de la Ciudad de Buenos Aires / CC BY 2.5 ar via Wikimedia Commons (file page).
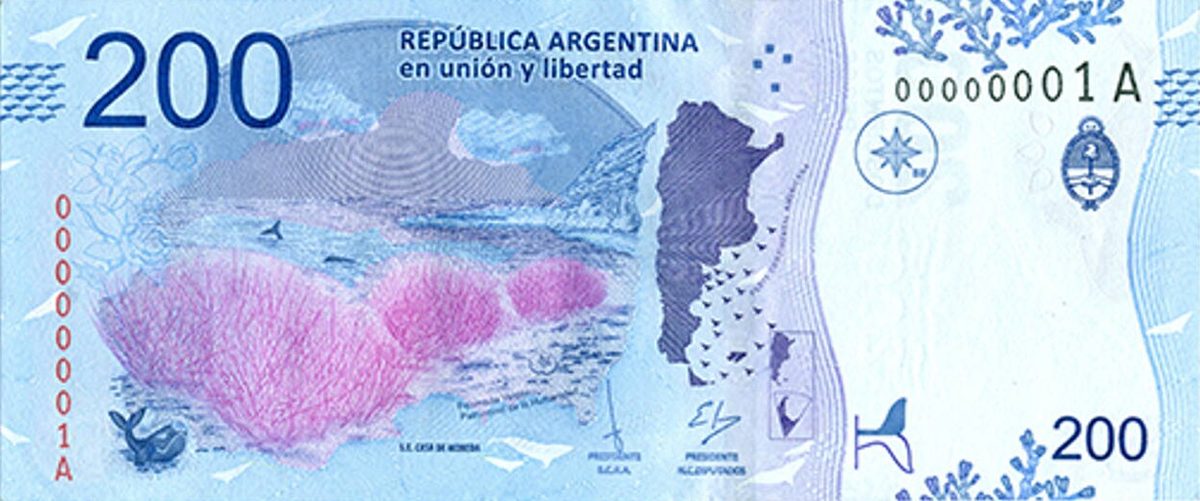
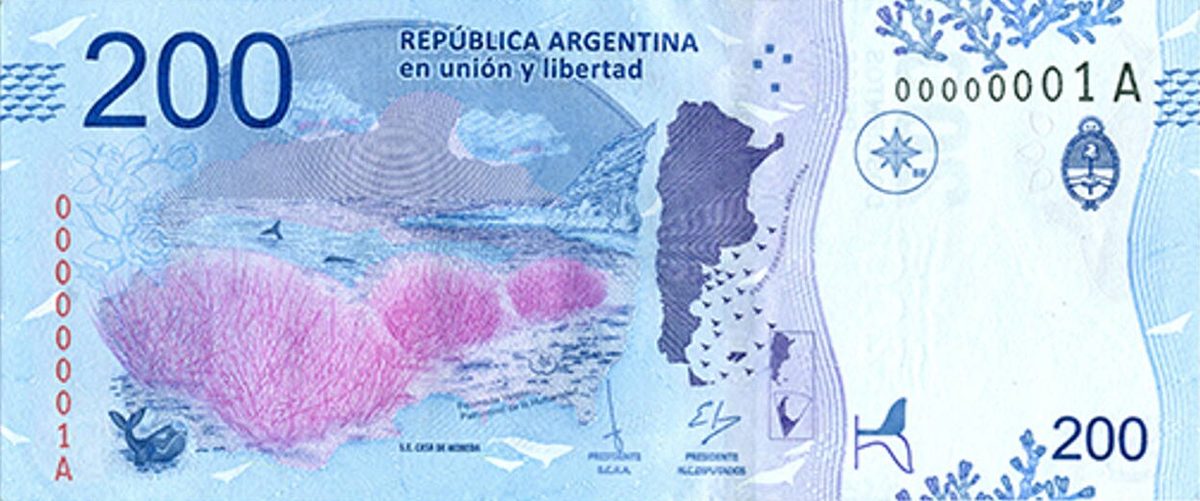
- Argentine 200-peso banknote — Photo: Casa de Moneda / CC BY-SA 2.0 via Wikimedia Commons (file page).